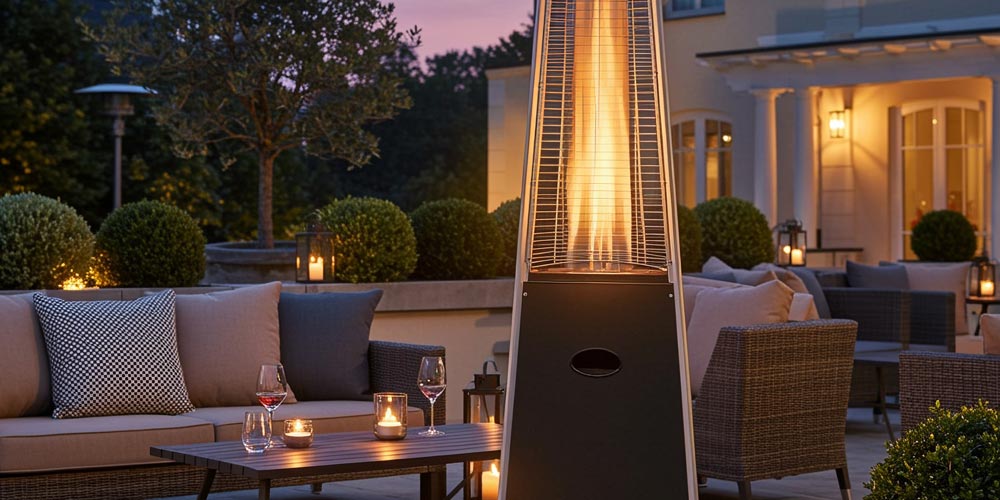
Outdoor heaters have become a natural part of outdoor living. Expansive patios, custom decks and outdoor entertaining areas often include kitchens, fireplaces, furniture, lighting and heating that allow homeowners to enjoy these spaces well into the colder months. For homeowners who have made a significant investment in their property, an outdoor heater may seem like a small addition, but it also introduces another source of fire and liability risk.
The Risk Goes Beyond the Heater
An outdoor heater does not exist in isolation. It may be surrounded by expensive furniture, custom structures, landscaping, outdoor kitchens and other features that represent a substantial investment. If a heater tips over, malfunctions or contributes to a fire, the resulting claim could involve much more than the equipment itself. Damage could extend to a deck, pergola, patio, exterior of the home or other property, while smoke and water from firefighting efforts could create additional damage.
This is why the insurance question is not simply whether the heater itself is covered. It is whether the overall property and the improvements surrounding it have been properly considered when determining the appropriate coverage.
Homes Require an Individual Approach
A homeowners property can change considerably over time. A new outdoor kitchen, pool, custom patio, landscaping project or other improvement can represent a significant investment, and the cost to repair or replace those features may be considerably higher than homeowners initially expect.
Those changes are worth discussing with your insurance professional to make sure coverage and limits continue to reflect the property as it exists today. The same applies to valuable personal property and other assets that may have been acquired since the last policy review.
Liability Protection Matters, Too
Outdoor spaces are often designed for entertaining, which creates another consideration. A guest could be injured by an outdoor heater or another condition on the property, potentially resulting in a liability claim. For homeowners with substantial assets, personal liability limits deserve careful attention, and an umbrella policy can provide an additional layer of protection above certain underlying policies.
The appropriate amount of liability protection is different for every household. It should take into account your assets, lifestyle and overall exposure rather than relying on a standard amount of coverage.
Review Your Coverage Before You Need It
An outdoor heater does not automatically mean your insurance needs to change. It is simply a good reason to look at the bigger picture, particularly when your home and outdoor living spaces represent a significant investment.
At AssetSure Group, we take a personalized approach to personal insurance, looking at each client’s property, assets, lifestyle and potential exposures to help identify coverage designed around their circumstances. After 50 years in the insurance business, we understand that protecting a home requires more than renewing the same policy year after year. Your insurance should keep pace with the property you own and the way you live.
To review your homeowners, personal liability and umbrella protection, contact AssetSure Group’s Personal Lines team at (888) 222-7476 ext. 290 or visit https://www.assetsuregroup.com.